

Illicit Finance in a Fragmenting World: Can the Global System Keep Pace?

Today’s financial integrity architecture took shape in an era of multilateral cooperation. Can it still be effective in a world divided by war and geopolitical rivalry?
The global system for combating illicit finance was built for a different world. Centred on the Financial Action Task Force (FATF), established at the 1989 G7 Summit in Paris, it emerged during an era of growing economic integration, expanding multilateral cooperation and a financial architecture dominated by the US dollar.
That world is disappearing. Geopolitical rivalries are intensifying, sanctions have proliferated, and technology is creating new ways to move and conceal value. The global financial order is fragmenting too. What is emerging is not one alternative system, but a growing variety of options, driven by states seeking strategic autonomy, countries responding to necessity and illicit actors spotting new opportunities.
As the UK’s 2025 National Security Strategy underlines, finance has become an increasingly important dimension of our security. It enables war, hybrid activity, proliferation, political interference and sanctions evasion. But correctly employed, it also provides the information and leverage needed to identify and disrupt these threats. Following the money has moved well beyond financial crime enforcement; it now has the potential to play a central role in national and international security.
Much of the global response, however, is rooted in frameworks designed for another era. This special issue of the RUSI Journal, ‘Illicit Finance in a Fragmenting World’, asks whether the current system remains fit for purpose and what must change if it is to keep pace.
Does the FATF Practise What It Preaches?
The 40 Recommendations of the Financial Action Task Force – the watchdog for the implementation of the global response to financial crime – have shaped laws, institutions and compliance systems across the world. Few international organisations exert such influence over domestic policy. Its own performance should therefore be open to scrutiny.
The biggest challenge of the current FATF framework is the gap between technical compliance and real-world effectiveness. Countries can pass the required laws, establish the prescribed institutions and produce extensive risk assessments without becoming noticeably better at detecting or disrupting illicit finance. Others may struggle to demonstrate formal compliance while confronting severe national security threats such as health emergencies or climate change challenges with limited resources.
So, does the FATF practise what it preaches? At one level, ‘yes’. It tells governments and financial institutions to take a ‘risk-based approach’ and direct their scarce resources towards the greatest risks. But it struggles to apply the same test to its own priorities, evaluations and use of resources, often seemingly rewarding the completion of prescribed tasks rather than recognising demonstrable impact and outcomes.
Equally important is its institutional capacity. A strong task force requires a strong Secretariat, especially when geopolitical divisions are making consensus harder to achieve. Preserving expertise, institutional memory and analytical independence would not weaken member-state leadership. It would help the organisation remain coherent when political agreement is under strain and respond more quickly when threats change.
Then there is the question of what mutual evaluations actually measure. Anti-money laundering (AML) systems do not operate separately from the states in which they are embedded. Governance, political commitment, institutional capacity and resources all determine whether apparently compliant structures produce meaningful results. Leaving out these conditions risks producing a misleading evaluation. We may learn whether the expected machinery exists, but much less about whether it works.
The bar does not need to be lowered. But we should be more honest about what it measures and what it misses. The FATF also needs to stay humble and listen. For a global standard setter, listening is more than diplomatic good manners. Its legitimacy depends on it.
Following the Money in a More Dangerous World
The illicit finance architecture was developed primarily to address the proceeds of crime and, later, terrorist financing. Yet illicit finance now encompasses an ever-wider spectrum of threats including the financing of war, hybrid threats, sanctions evasion and state-directed interference. The framework has not fully caught up with the changing and fragmenting geopolitical landscape.
Russia’s war against Ukraine makes this difficult to ignore any longer. The illicit financing of hybrid threats is bringing together hostile state agencies, organised criminals, cut-outs and apparently legitimate businesses. A transaction that looks unremarkable on its own may take on an entirely different meaning once it is connected to the people, relationships and activities behind it.
But financial institutions are generally expected to identify suspicious transactions, not reconstruct the architecture of hostile state activity. Financial intelligence units and law-enforcement agencies are still organised around criminal categories that fit awkwardly with conduct spanning crime, national security and warfare. Better indicators would help, but they will not solve the problem on their own. Financial, corporate, political and security information needs to be brought together far more systematically.
Consider the infrastructure supporting the abduction and militarisation of Ukrainian children. A focus on prominent officials can obscure the camps, administrators, transport providers, businesses, banks and other facilitators that allow the activity to continue. Sanctions designed around this wider network stand a better chance of disrupting the conduct than repeated designations aimed principally at its public face.
Another factor that is revolutionising global finance is technology. It raises a different set of challenges – and requires a change in mindset. For example, blockchain investigations are still portrayed as prohibitively complex and dependent on costly tools. In practice, the disciplined identification and labelling of wallets can expose significant illicit activity. Information is not always the missing ingredient. Frequently, the real problem is a failure to develop, analyse and share what is already available.
Proliferation financing, which has been a cornerstone of FATF efforts, also remains too narrow. National proliferation-financing risk assessments tend to focus heavily on North Korea and Iran, and related UN sanctions. Both are important, but they do not represent the full range of actors, technologies, intermediaries and procurement networks that may exploit a country’s economy. A genuinely national assessment should not simply reproduce the international community’s established list of risks. It should begin with national exposure.
The most striking blind spot may be the financing of war itself. Conflict depends on money, procurement networks, commercial relationships and access to financial services. Still, conflict financing is not treated as a distinct, cross-cutting financial crime risk. That is difficult to defend when so many jurisdictions under enhanced FATF monitoring are also affected by war or severe instability.
Who Bears the Cost?
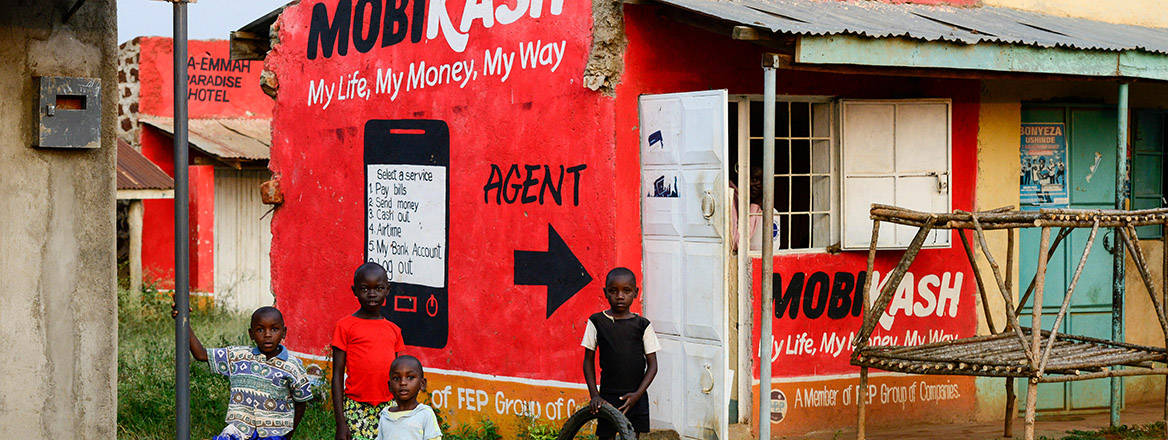
The countries that had the least say in how the system was designed are often the ones most affected by its flaws. Many jurisdictions in the Global South face serious threats from corruption, kleptocracy and illicit financial flows. At the same time, they bear a relatively disproportionate share of the cost of international compliance.
Governments must finance increasingly complex systems to meet international requirements. If they fall short, greylisting can restrict access to finance, raise transaction costs, deter investment and place further pressure on already stretched institutions. A mechanism intended to accelerate reform may end up making that reform harder.
Lower-income countries should not be held to weaker standards, but a risk-based approach should be applied by the FATF. Identifying deficiencies and threatening a listing does not necessarily result in improvement, particularly in contrast to the financial system harms facilitated by international financial centres. Progress requires sustained engagement, properly prioritised assistance and a realistic understanding of the country’s political and institutional environment.
Nor are governments the only ones affected. Measures intended to prevent the abuse of non-profit organisations have restricted legitimate civil society activity in parts of sub-Saharan Africa. Despite revisions to FATF Recommendation 8, blanket and disproportionate implementation persists at best, with authoritarian regimes abusing these standards at worst. Organisations operating in already difficult environments may face greater surveillance, higher compliance costs or exclusion from financial services. A standard intended to protect civil society should not provide cover for closing civic space.
This gives FATF-style regional bodies an especially important role. They can help prevent reform overload by translating global expectations into regional practice, supporting peer learning and helping governments separate immediate priorities from longer-term ambitions. They are sometimes treated as the system’s supporting cast. In reality, much of its success – as recognised by the recent Mexican FATF presidency – depends on them.
What Needs to Change
The contributions to this Journal issue do not add up to a single rulebook with all the answers. But they expose weaknesses that are becoming harder to overlook.
Central to the future of the FATF and its global standards is genuine risk-based decision-making, which needs to be visible in priorities and resource allocation, rather than confined to official language. Financial intelligence must respond to threats that cross the traditional boundary between crime and national security. And the system will struggle to retain legitimacy while jurisdictions bearing some of its greatest costs remain peripheral to decisions about its future – and to the threats the system is designed to address.
The FATF and the wider financial integrity architecture have achieved something remarkable. They have established a global expectation that countries should protect their financial systems from abuse. But past achievement is no guarantee of future relevance.
What the system needs is a better grasp of emerging threats. This means investing more in regional capacity and speaking more honestly about who bears the costs of global standard-setting. It also demands better listening: to journalists and civil society investigators confronting new forms of hostile activity, governments struggling to turn recommendations into operational results and communities living with the unintended consequences of compliance.
Prefer to Watch or Read?
If all this still feels rather distant from everyday life, we also have a television recommendation. Steal brings many of these issues to the screen, including offshore structures, professional enablers, cryptocurrencies and hidden beneficial ownership. The criminals and their plot may be fictional. The frustration of investigators trying to trace money across jurisdictions is not.
For those who would rather grab a book and take a deeper dive, the Journal reviews two timely contributions. Everybody Loves Our Dollars: How Money Laundering Won traces the origins and shortcomings of the international system for combating financial crime, including its tendency to scrutinise smaller jurisdictions while its most powerful members avoid equivalent attention.
Doing Business with Criminals: Between Exclusion and Surveillance poses a different question. Should criminals be excluded from the financial system, or kept inside it so that their activities can be monitored? It is a contradiction at the heart of the AML system and one without a comfortable answer.
Whether you prefer policy analysis, a good book or an evening in front of the TV, there is more than one way into this debate.
The world in which the FATF was created no longer exists. The need for collective action against illicit finance has rarely been greater. Whether the system can adapt quickly enough is the question this issue put to its contributors and now to its readers.
© RUSI, 2026.
The views expressed in this Commentary are the author's, and do not represent those of RUSI or any other institution.
For terms of use, see Website Terms and Conditions of Use.
Have an idea for a Commentary you'd like to write for us? Send a short pitch to commentaries@rusi.org and we'll get back to you if it fits into our research interests. View full guidelines for contributors.
WRITTEN BY
Kinga Redlowska
Head of CFS Europe
Centre for Finance and Security

- Jim McLeanMedia Relations Manager+44 (0)7917 373 069JimMc@rusi.org