

Bibi and the Blockchain: When a Prime Minister Plans for Sanctions Evasion

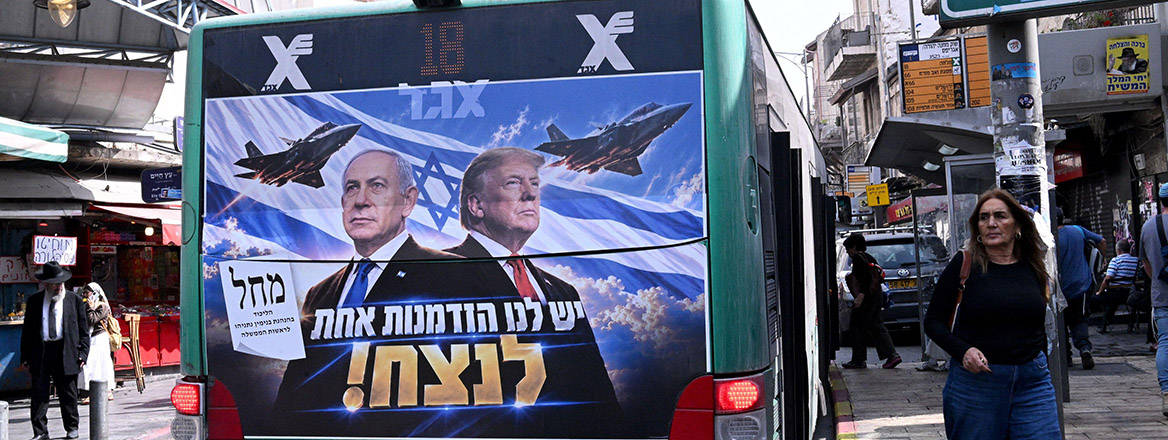
Benjamin Netanyahu’s interest in cryptocurrency reveals both the continuing power of financial sanctions and the current limits of technological attempts to circumvent them.
Thanks to the widely reported efforts of the Russian Federation, it is no longer fantasy that cryptocurrency and blockchain-based payment systems can help sanctioned actors move money, circumvent restrictions and sustain particular commercial relationships. But importantly, while crypto might facilitate payments, its use cannot replicate the broader economic benefits of access to the international financial system. Governments considering crypto as protection against financial isolation risk confusing the ability to transfer value with the ability to participate in the global economy.
While Russia’s experience provides the principal case study of both the possibilities and limitations of alternative financial arrangements, the recent Israeli debate, in the days before the 27 October election, provides a particularly revealing illustration of how these considerations are spreading. Appearing on Israel’s Channel 10 TV station, Netanyahu said he was preparing for the possibility that sanctions would be applied against Israel. This is not speculation. In September, the UK and other Western governments announced their intention to apply sanctions and trade measures against certain elements of the Israeli economy in response to, in the words of UK Foreign Secretary Ed Miliband, the unlawful occupation of the Palestinian Territories, specifically against ‘those who finance or facilitate illegal settlements’.
In particular, he noted that ‘There could be sanctions, and sanctions on banks, so you need to set up a bypass economy’ using currencies – including cryptocurrency – that can bypass sanctions, revealing in conclusion that ‘we are also working on that’.
His comments were met with criticism by the Bank of Israel that suggested he would do better to focus on policies that did not require such measures, noting that ‘The right course for Israel’s economy is to preserve our economic relations with our main trading partners, and to focus on preventing sanctions and their negative impact on the economy.’ An open letter signed by more than 100 economists also poured scorn on Netanyahu’s actions, saying that he is ‘knowingly leading the State of Israel toward boycott and international economic isolation, and all he has to offer the Israeli economy is a puzzling solution, one accepted in criminal organisations, that will not help in the slightest’.
While tactical advantage might be secured, running an entire economy – particularly as developed as Israel’s – through the so-called ‘cryptoverse’ remains out of reach
His political opponent, Gadi Eisenkot, likewise ridiculed the plan as ‘madness’, calling it the ‘BibiCoin policy’ and predicting it would encourage Israeli companies to move abroad and threaten national security.
Regardless of the merit of the idea, it is striking in itself that a sophisticated, internationally integrated economy such as Israel is contemplating alternative financial arrangements in anticipation of possible sanctions. The fact that its leadership apparently regards sanctions as a credible economic threat will not have escaped notice in those countries – including the UK – that have threatened sanctions in response to the further expansion of Israel’s illegal settlements. Sanctions may not change Israel’s behaviour towards settlements in the occupied territories, but the threat of application certainly has the potential to cause disruption.
Zooming out from the specifics of Israel, Netanyahu’s comments pose an important question: have crypto and the blockchain matured sufficiently to allow a country to pre-emptively crypto-proof itself against sanctions? The attraction is alluring, particularly when a government anticipates looming financial isolation. If conventional banking relationships are likely to be interrupted, why not build an alternative system that cannot be so easily disrupted?
The experience of other sanctioned countries such as Russia, Iran and other actors that have already explored alternative financial systems is that while tactical advantage might be secured, running an entire economy – particularly as developed as Israel’s – through the so-called ‘cryptoverse’ remains out of reach, even for such a technically sophisticated country. Accessing sufficient crypto liquidity, identifying the necessary range of trading partners who will deal in crypto, and rewiring an economy to accommodate such a move are all immense (and mostly insurmountable) challenges.
Bibi’s vision rests on a fundamental misunderstanding of what makes financial sanctions powerful for a globally integrated economy: the ability to move money is not the same as the ability to participate in the international economy.
What Do Sanctions Actually Do?
This might seem like an obvious question, but much of the rhetoric on sanctions – particularly from political leaders – is misguided and aspirational, and it is thus important to ensure expectations are correctly set.
Sanctions do not switch off the target’s economy. Consider the extent to which – and the way in which – Russia’s economy has continued to function. But sanctions do force an economy to reshape and rewire, adding friction and cost, and forcing the country’s leadership to make choices. Thus, while banks are required to stop processing payments, the core power of sanctions stems from their ability to restrict access to the complex network of global institutions, services, markets and commercial relationships that allow a developed economy like Israel to function.
The plumbing of the international commerce that enables an economy and its exporters and importers to function includes correspondent banking, trade finance, credit, insurance, investment, reserve management and the engagement of trusted finance and trade counterparties. Sanctions create legal, regulatory, reputational and commercial risks that affect all these relationships – and secondary sanctions and the prospect of losing access to major markets amplify these risks and the resulting effects.
In short, running a nation’s economy depends on far more than merely enabling payments settlement.
So, What Could Cryptocurrency Actually Do?
It would be wrong to dismiss the use of cryptocurrency outright. Russia has very effectively developed crypto-based payment systems that allow it to pay for the procurement of the critical high-priority list items it needs to wage its illegal war of aggression in Ukraine. It is thus important to recognise these advantages to understand both the appeal (even if misplaced) and the limitations of the greater adoption of crypto in the face of sanctions.
Let us start with the legitimate appeal. Crypto can enable cross-border value transfers without relying on traditional correspondent banking arrangements; stablecoins, such as USDT from Tether, can provide a relatively convenient means of transferring dollar-denominated value; and peer-to-peer transactions, decentralised systems and intermediaries operating in permissive jurisdictions can make sanctions enforcement more difficult. All of these features will seem alluring to a political leader faced with the impact of major financial restrictions stemming from broadly arrayed sanctions.
Russia’s development and use of alternative financial systems, most famously the A7 payment platform, which has been openly backed by Vladimir Putin, demonstrates that such mechanisms are not merely theoretical. In short, crypto can support specific transactions, intermediary networks and sanctions-circumvention operations.
But can crypto support the operation of an entire economy, particularly one as large (the 25th largest in the world), networked, and exposed to the West, as Israel’s?
Three fundamental – and existential – challenges exist. First, liquidity, scale and reliable conversion will present material constraints. There simply is not enough capacity in the cryptoverse to accommodate any but the smallest economies. Second, stablecoins introduce meaningful risk dependencies (just look at the 29 October Binance hack) that the traditional financial system has spent decades addressing. And third, crypto might provide an alternative payment mechanism for an individual transaction, but providing an alternative market for a country’s exports is another question entirely, which would require a rewiring of counterparty nations’ payment systems to accommodate such a transformation.
Circumvention is Not Substitution
As widely studied and reported, Russia provides the most instructive contemporary example of the distinction between circumventing particular restrictions and replacing the entire basis on which a country interacts with the international financial system.
Since triggering wide-ranging financial sanctions and economic restrictions on itself as a result of the Kremlin’s 2022 full-scale invasion of Ukraine, Russia has made considerable strategic investment in developing alternative payments infrastructure, including bilateral settlement arrangements (with Iran) and broader mechanisms designed to reduce dependence on Western financial institutions and markets.
Cryptoassets have become elements of this effort – but not uniquely. Russia has also relied on third countries for trade circumvention, opaque corporate structures and ledger systems for offshore payments, and a range of other obfuscation and evasion tactics.
The breadth and complexity of this range of arrangements demonstrate the need for adaptability and the extent to which sanctions evasion requires an array of tools.
Governments considering the adoption of crypto as insurance against sanctions should recognise what they are proposing
The result? Russia has maintained substantial international trade despite sanctions, but the mechanisms it has needed to use are often more costly, less efficient, more time-consuming and more risky than those it used previously. Is that what Israel wants?
The Sovereign Crypto Illusion
Thus far, the focus has been on what the government of a country targeted by sanctions can do – what it can almost certainly not do is compel the rest of the world to sign up to the same mission. For example, is a foreign supplier going to have confidence that it will receive the same trusted value via a new blockchain-based ‘currency’; and are third-country facilitators of such a scheme (for example banks converting stablecoins into local currency) going to be willing to run the risk that they too may become subject to sanction as a result? Financial sovereignty is inextricably linked to the willingness of other economic actors to trust, accept and use the proposed system.
Will Bibi’s Blockchain Bypass Work?
So, can Bibi use the blockchain to set up a bypass economy? In short, no. Could certain payments be moved from the traditional banking system onto the blockchain? Yes – this is what Russia has done to pay for many of the critical components it needs for its military. But that does not isolate those payments or those that facilitate them from further sanction and disruption. The only way to do that is to follow the advice of the Israeli central bank and ‘focus on preventing sanctions and their negative impact on the economy’.
More broadly, governments considering the adoption of crypto as insurance against sanctions should recognise what they are proposing. Crypto may offer a means of moving money when conventional routes are closed, but it cannot guarantee that anyone will want to receive that money, provide credit, insure a shipment or invest in the economy. Building an alternative payments system is not the same as building an alternative means of engaging with the international economy.
© RUSI, 2026.
The views expressed in this Commentary are the authors', and do not represent those of RUSI or any other institution.
For terms of use, see Website Terms and Conditions of Use.
Have an idea for a Commentary you'd like to write for us? Send a short pitch to commentaries@rusi.org and we'll get back to you if it fits into our research interests. View full guidelines for contributors.
WRITTEN BY
Tom Keatinge
Director, CFS
Centre for Finance and Security

- Jim McLeanMedia Relations Manager+44 (0)7917 373 069JimMc@rusi.org